Double Kill Game of US Dollar and US Bond, Gold Equity Welcomes Opportunities
On February 12, the US January non-agricultural employment data grew stronger than expected, which directly triggered sharp fluctuations in the US bond market, with the pressure on short-term varieties being particularly significant. The market significantly adjusted the pricing of the US Federal Reserve's interest rate cut in 2026. On the same day, the US treasury bond auction also showed that the market's demand for US bonds was weak. For various reasons, the market needed higher yields on US bonds, which also made the US government's debt crisis more foggy.
Fluctuations in the US Treasury Market: Short term yields lead gains, curve shape fine tuned
After the release of the non-agricultural data, US Treasuries suffered a sell-off, and the price fell rapidly. The short end of the yield curve rose significantly more than the long end. Finally, the yield of two-year, five-year, and 10-year treasury bond bonds quickly stretched 1-2%, and then went out of the trend of rising and falling.
The yield of two-year US Treasury bonds ultimately rose by 6 basis points in a single day to 3.51%, stabilizing near the critical threshold of 3.5%; The yield of 10-year US Treasury bonds rose by 3 basis points to 4.17%, with narrow fluctuations in the long short spread.
This trend reflects the market's repricing of the Federal Reserve's policy interest rate path - the timing of the first interest rate cut in June that the money market had previously bet on has been postponed to July, the probability of a rate cut in March has plummeted to less than 5%, and the expected cumulative rate cut for the whole year has shrunk from 59 basis points to 52 basis points.
Among other assets linked to US Treasury bonds, the US dollar has shown range fluctuations and has not shown a significant upward trend. In the past, when US Treasury bonds rose so rapidly, the US dollar would actively follow suit, revealing several fatal signals.
One is that the yield of US Treasury bonds is usually a very stable commodity, and the recent rapid rise in the market indicates that there is a serious selling sentiment in US Treasury bonds, combined with the weak rebound of the US dollar index, creating a picture of a US dollar credit crisis.
In addition, the simultaneous sale of US dollars and short-term US Treasury bonds in the market indicates a shift in funds from traditional safe haven assets, suggesting that there may be opportunities for gold and US stocks.
From the closing performance, it can be seen that Nasdaq usually has a significant valuation killing effect when the unemployment rate rebounds, wage income rises, and the number of non farm employees increases, combined with a tight labor market. Similar to the increase in labor costs for companies and the rise in valuation discount rates, Nasdaq is hit hard by a double blow, resulting in a strong performance. This also confirms the hypothesis of capital transfer from US dollars to US bonds.
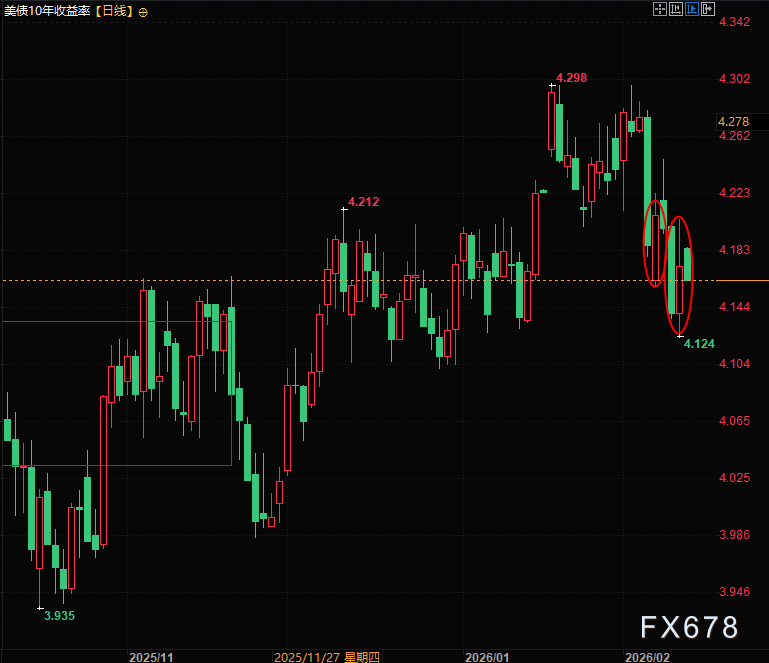
(Daily chart of US 10-year treasury bond bond yield, the overall decline is beneficial to gold and equity assets)
Core driver: Non farm data exceeds expectations, key to stabilizing labor market
In January, the US added 130000 non farm jobs, the largest increase in over a year, and the unemployment rate unexpectedly fell to 4.3%. This double positive confirms the continued stabilization of the labor market and directly weakens the necessity for the Federal Reserve to cut interest rates in the short term.
It is worth noting that the employment data for the previous year was significantly revised downwards, with an average of only 15000 new jobs added per month last year, far below the initial value of 49000. However, the strong rebound in January data still exceeded the expectations of all economists, forming a pattern of "downward revision of the base but stronger month on month".
Another key highlight of this non farm payroll is that US manufacturing employment has turned positive for the first time since the end of 2024, sending a positive signal that the manufacturing industry is breaking away from its long-term slump.
In subsequent statements, the White House viewed this change as a sign of the effectiveness of industrial policies, and the overall stabilization of the labor market echoed the decision basis of the Federal Reserve's "pause in interest rate cuts" at last month's meeting, further strengthening market expectations for policy stability.
Morgan Stanley Wealth Management's Allen Zentner pointed out that last week's weak data had led the market to predict a weakening of non farm payrolls, while the strong recovery of the actual job market directly broke the pessimistic expectations of an economic slowdown and became the core driving force behind the rise in US bond yields.
Policy expectation repricing: shrinking room for interest rate cuts, supporting hawkish stance
The strong non farm payroll data provides strong support for the hawkish Fed, and the market's judgment on the policy path has significantly shifted.
Kansas City Fed President Jeff Schmidt has made it clear that interest rates should be kept within a "restricted range," and the current high inflation levels still require vigilance.
This stance resonates with the market's contraction of expectations for interest rate cuts, driving a significant increase in short-term US bond yields - as the most sensitive product to policy rates, two-year US bonds directly reflect the market's pricing adjustment for the Federal Reserve to maintain high interest rates.Societe Generale Investment
The expectations of institutions for the magnitude of interest rate cuts have also diverged. TD Securities still maintains its expectation of a 75 basis point rate cut in 2026, but emphasizes that the rate cut will be a "policy normalization" after inflation approaches the 2% target, rather than a loosening forced by economic weakness;
Krishna Guha of Everton believes that if the strong employment trend continues in January, it will be difficult for the Federal Reserve to cut interest rates three times a year; Bank of America focuses on the policy direction of Federal Reserve Chairman nominee Walsh, maintaining the benchmark expectation of "two rate cuts", but warns that if the unemployment rate continues to decline, Walsh may keep interest rates unchanged for the rest of the year.
Mike Reid from Royal Bank of Canada Capital Markets emphasized that the non farm payroll data in January clearly showed a continuous improvement in the job market, which confirmed the Federal Reserve's judgment of a "long-term pause in interest rate cuts" in 2026. However, he also cautioned against overinterpreting monthly data and emphasized the need to pay attention to more verification signals in the future.
Outlook for Institutional Trading: Focusing on the volatility of yield ranges, CPI becomes the next key variable
For subsequent US Treasury trading, institutions generally believe that the policy expectation repricing has not yet ended, and the yield will exhibit interval volatility characteristics.
Angelo Kurkafas of Edward Jones pointed out from the perspective of asset allocation that the 10-year US Treasury yield is expected to return to the middle of the 4% -4.5% range, which has become an important reference for current institutional layouts of medium - and long-term US Treasury positions.
The core variables for subsequent transactions will focus on the core CPI data released this Friday.
Kay Hagrid from Goldman Sachs Asset Management stated that the job market is showing signs of tightening again, and the economy's unexpected performance will prompt the Federal Reserve to shift its policy focus entirely towards inflation. If CPI exceeds expectations, the Federal Reserve's policy may further shift towards hawkishness, driving US bond yields to continue rising;
Morgan Stanley's Michael Gappen also emphasized that the core of interest rate cuts still depends on the pace of inflation decline, and the strengthening of non farm sectors only reduces the probability of short-term interest rate cuts, without changing the core logic of "inflation led easing timing".
According to the calculations of JPMorgan's trading team, if the core CPI meets or falls below expectations (economists expect a 0.3% month on month increase), the rise in risk assets may indirectly suppress the upward trend of US bond yields;
If CPI increases by 0.4% or more on a month on month basis, although it may trigger a sharp decline in the US stock market, US bonds may receive support due to hedging needs, but the probability of this scenario occurring is relatively low.
Summarize:
Overall, the January non farm payroll data has dominated the recent trading logic of US Treasury bonds by reshaping the Federal Reserve's policy expectations.
In the short term, the yield of US Treasury bonds will fluctuate within a range around the policy path game, and short-term varieties will still be most sensitive to changes in interest rate cut expectations;
In the medium to long term, inflation data and the sustainability of the labor market will become the key factors determining the trend of US Treasury bonds. Investors need to focus on resonance or divergence signals between policy expectations and fundamentals, and seize trading opportunities in yield fluctuations.
However, the 10-year US Treasury auction did not meet expectations, with US bonds rising and the US dollar not keeping up, implying concerns about US government debt and doubts about US dollar credit. Coupled with Texas launching its own gold linked currency, the wave of selling off the US has not ended. At the same time, the 10-year US Treasury yield secondary market still shows a downward trend, leading to a downward shift in long-term interest rates, and opportunities continue to come to assets such as gold and US stocks.
Please indicate the source when reprinting: https://www.daoctech.com/fxoutrade/5265.html
Disclaimer: The content of this article does not represent the views of the Institute of Foreign Exchange. The content is for reference only and does not constitute investment advice. Investors operate accordingly at their own risk.