
The historical warning of gold development: every glory is accompanied by the test of objective figures.
On Thursday (November 6), spot gold in Asia and Europe continued yesterday's rebound pattern. It is currently up 0.85% and trading near $4012. Among the popular safe-haven varieties in the market, the US dollar, US debt, and gold have gone hand in hand. Recently, the performance of US dollar and US debt has been eye-catching. Today, it began to adjust, and gold took the opportunity to start a rebound.
The US AI bubble narrative, government shutdowns, geopolitics, and other issues continue to support safe-haven buying. This article quotes recent remarks from the investment director of AJ Bell to provide readers with some historical observations on gold.
Russ Molde, investment director at AJ Bell, said that since 1971, gold is in the third major bull market, and there have been deep retractions in the previous two bull cycles, but this cycle, government debt, geopolitics, dollar movements and inflation factors will continue to drive gold prices higher.
The first bull market (1971-1980): the collapse of the gold standard + inflation-driven fluctuations
The first bull market mentioned by Mr. Molde began when President Nixon abandoned the gold standard and dismantled the Bretton Woods monetary system, noting that "as the Nixon administration began to widen the US federal deficit, inflation surged, and the effects of two oil price shocks, gold prices rose from $35 an ounce in August 1971 to a peak of $835 an ounce in January 1980."
Although gold investors have been able to avoid the shock of severe inflation, the investment process has not been smooth sailing.
"Even during the glorious 1970s rally, there were no fewer than three mini-bear markets - in 1973, 1974 and the January 1975-1976 summer, which lasted more than 18 months, during which gold fell more than 20 per cent.
To further test the resilience of bulls, gold has also experienced five 10% -20% pullbacks, which occurred in 1972, 1973, 1977, 1978 and 1979. "
Mr. Molde said that while the last two pullbacks lasted only a month, "they are a test of the resolve of gold bulls even against the backdrop of a near-straight rise in gold prices in the final sprint of the bull market."
"Then, against the backdrop of Paul Volcker's Federal Reserve and the UK's Thatcher government's efforts to contain inflation, gold went dormant - aided by deregulation on both sides of the Atlantic, a return to peace in the Middle East and lower oil prices," he wrote. "Double-digit interest rates also made the opportunity cost of holding gold unbearable."
The second bull market (2001-2011): easing policy + safe-haven demand, peaked after shock
But when gold prices bottomed out above $250 an ounce in 2001, it attracted "a new generation of investors who sought refuge from ultra-loose monetary policy after the bursting of the tech, media and telecoms bubbles in 2001-03 and the global financial crisis in 2007-09," Mr. Molde said. "Some investors saw gold as an ideal target in the face of zero interest rate policy (ZIRP), quantitative easing (QE) and balance sheet expansion as markets began to chase stores of value or safe-haven assets."
"Even in this second rally, gold struggled to test the resolve of believers, with two bear markets in 2006 and 2008, and a pullback of more than 10 per cent each in 2003, 2004, 2006, 2009 and 2010," he noted.
Gold prices peaked at nearly $1,900 an ounce in 2011 and then fell to around $1,000 an ounce in 2015 as central banks regained control of the market after the global financial crisis.
"Mario Draghi's commitment to stability in the eurozone at all costs in 2012 was also seen as a warning sign, and the low growth, low inflation environment led many to believe that markets had calmed down and gold's safe haven function was no longer needed, especially after the European Union debt crisis appeared to have subsided," he said.
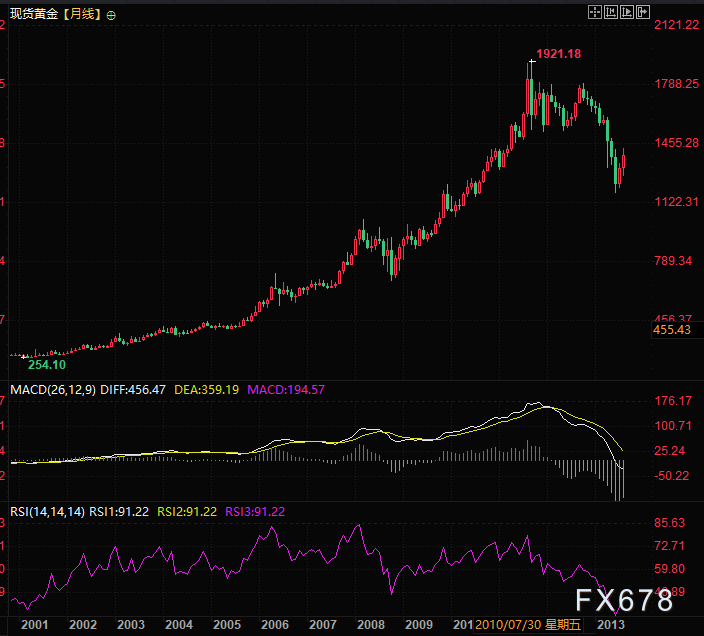
(Spot gold weekly chart 2001-2011)
The third round of bull market (2015-present): early start + continued volatility, support factors have not changed
But after 2015, Molde noted, gold began to rise quietly, "well before the COVID-19 pandemic, lockdowns, massive government financial support, not to mention tariffs and trade wars, new turmoil in the Middle East, and conflicts in Eastern Europe."
"Perhaps gold is signalling that central banks will find it difficult, if not impossible, to move away from zero interest rates and quantitative easing, and that their balance sheets will continue to swell - a view that the Fed's suspension of quantitative tightening (QT) this autumn is a testament to its relevance to this day."
He pointed out that this third multi-year bull market also saw a bear market phase and a sharp correction.
"In 2022, as the world recovers from lockdown, gold prices plunged by more than 20 per cent, catching some bulls off guard, while the annual pullbacks of more than 10 per cent in 2016, 2018, 2020, 2021 and 2023 show that volatility has never left the market."
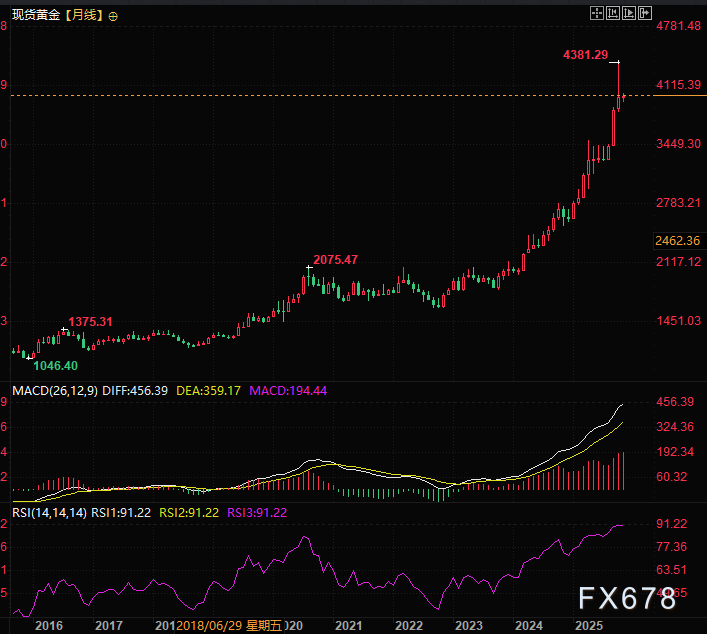
(Spot gold weekly chart 2015-2025)
Gold prices rose sharply every year, but the correction did not change the long-term trend
"Gold has rallied 45 per cent in dollar terms over the past 12 months, dwarfing the Nikkei 225, Nasdaq Composite and Hang Seng Technology, and raising questions about how far it can climb before it takes on the characteristics of a bubble," he wrote in a recent analysis.
"Skeptics who still see gold as a barbaric relic, a useless metal with no return, or even that the cost of holding gold is as high as 4% (due to the loss of cash interest income) may agree when the price of gold fell from its all-time high last month, but this correction does not necessarily mean the end of the rally.
There were multiple pullbacks in both bull markets in 1971-1980 and 2001-2010, but these pullbacks did not ultimately reverse or hinder the sharp gains in gold prices. "
However, it is worth noting that history cannot represent the future. The so-called long-term trend may be 5 years or 10 years.
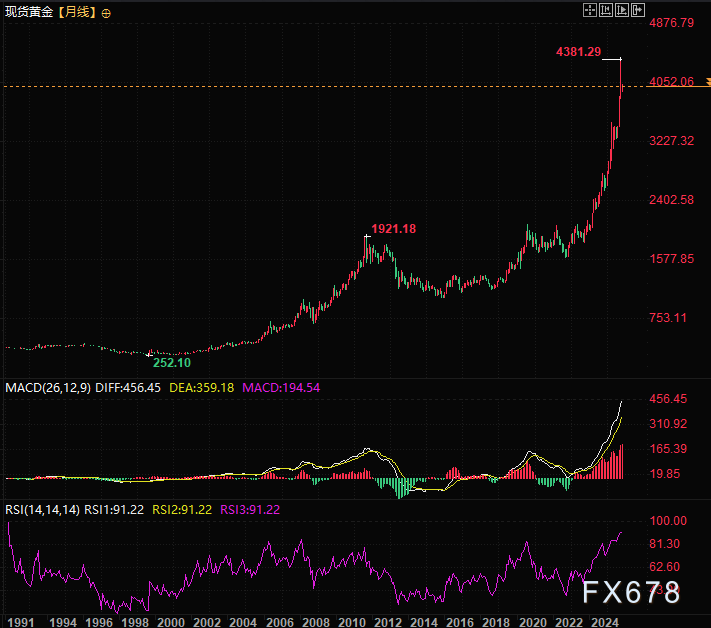
(Weekly chart of spot gold, 1991-2025, source: Internet)
Current Core Drivers: Debt, Inflation, and Geopolitical Risk Resonance
Molde said that all of this is closely related to the current rally and the current economic and financial challenges.
"Surging government debt and interest payments have led gold bulls to believe that zero interest rate policy and quantitative easing may be back in the policy toolkit of central banks, especially now that some seem less willing to hold US Treasuries and dollar assets than they used to for political, economic or financial reasons," he wrote.
"If rising debt, sticky inflation, geopolitical conflicts and political and fiscal policy pressures on central banks and monetary authorities have all played a role in this rally, it is reasonable to assume that investors will wait until at least some of these risks subside before moving away from gold again - although that day will come sooner or later.decodeforeign exchange”
Peak Judging Indicator: Gold's Affordability Threshold
"At the same time, one potential indicator of whether gold is near the peak of this cycle is its affordability," Mr. Molde said. "One way to judge is to look at how much gold the average household can buy if they spend their annual income. If the price of gold is beyond the reach of the average worker (or even the average investor), at least some incremental buying will be suppressed."
He points out that "before President Nixon took the US off the gold standard in August 1971 and dismantled the Bretton Woods monetary system, an ounce of gold was equivalent to less than 1 per cent of the average American household's annual disposable income".
"It peaked at more than 9 per cent in the late 1980s, at the end of the great 1970s gold bull market."
"In this dimension, the current ratio of nearly 6.5 per cent suggests there may still be room for gold prices to rise, especially if inflation starts to pick up and income growth is driven by higher wages or asset prices."
However, it can be seen from the figure that the growth rate of gold prices can be said to have exceeded the growth rate of disposable income for the first time, and it can also be said to be the first time in history. This is a very alarming thing
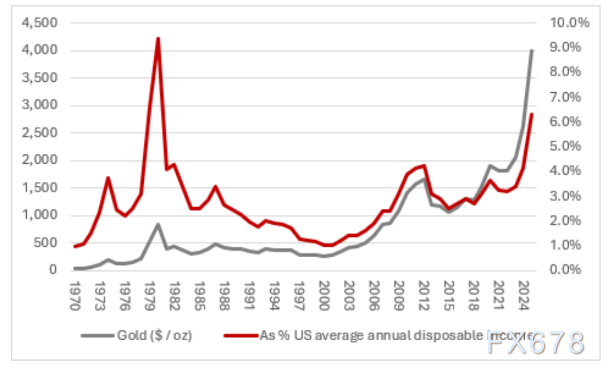
(Overlay of gold prices and US disposable income)
Please indicate the source: https://www.daoctech.com/fxschool/5218.html
Disclaimer: The content of this article does not represent the views of the Institute of Foreign Exchange. The content is for reference only and does not constitute investment advice. Investors operate accordingly at their own risk.