
Assessment of the impact of the situation in Venezuela: short-term disturbances and long-term prospects
Jen Yoon, chief executive of Fibonacci Asset Management, said in an interview that the current focus of market volatility observation is "whether the market is in a moderate hedging operation after this event or an influx of large-scale safe-haven buying".
Markets are caught between a trade-off and a wait-and-see: whether the Venezuelan affair will be a turning point in the adjustment of political risk weights in asset pricing, or will it become another news-side disturbance that fades rapidly and is difficult to change the logic of portfolio allocation.
It can be seen that the relevant news headlines are disturbing and have begun to ferment. Up to now, the market has also spread from obvious restraint to a comprehensive response. The current market volatility is reflected in a shift from moderate hedging operations to an increase in the scale of safe-haven buying.
Investors are closely monitoring a range of key signals, seeking to distinguish short-term news shocks from material economic transmission effects through the price signals of investment products. For investors who follow macroeconomic changes, professional institutions such as Xingye Investment usually provide in-depth analysis to help assess the true logic behind market fluctuations.
Focusing on oil market structure rather than spot prices
To determine whether the situation in Venezuela will have a systemic impact on the market, the first test is not the current crude oil spot price, but the overall term structure of the oil market.
Billy Liang, senior investment strategist at Global Exchange Traded Funds, noted that "the core is whether the oil market will tighten, as long as Brent crude remains around $60 a barrel and the forward curve remains contango, it means that the market is sending a signal of abundant supply and that investors have limited concerns about the risk of supply disruptions caused by the situation in Venezuela."
"Once the forward curve switches to the discount structure, it indicates that the supply problem has evolved from a mere news event to a material risk, although this has not yet happened."
When a crisis truly threatens crude oil supplies, buyers typically rush to snap up spot crude, pushing near-term contract prices higher than forward contract prices, creating a market structure known as backwardation, a classic sign of supply shortages or market panic.
At present, WTI crude oil has maintained a backwardation, which was in place before the event, while Brent crude oil is also a backwardation structure. At the same time, there are premiums in February and March, and forward discounts represent that the overall term structure of crude oil has indeed been affected by Venezuela, but the impact currently shows only 1-3 months.
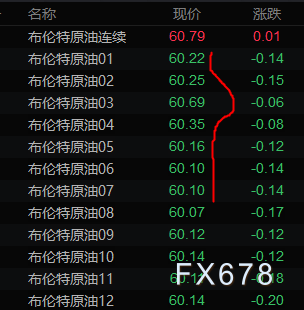
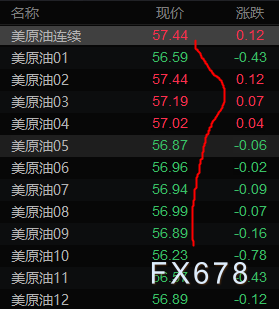
(Both Brent crude oil and WTI crude oil have a backwardation structure with proximal premium and distal premium, and only proximal 1-3 months premium)
Until the oil curve shows signs of a worsening tightening, investors generally believe that the situation in Venezuela does not pose a threat to the global energy system.
This view is also widely shared by industry insiders in the energy sector. Venezuela's crude oil production is about 1 million barrels per day, accounting for only about 1% of the total global supply.
In addition, the country's core energy infrastructure remains in normal operation. Other energy experts pointed out that the Organization of the Petroleum Exporting Countries and its allies have suspended plans to increase production, global crude oil inventories are at an abundant level, and the pattern of oversupply remains the core factor that dominates the trend of oil prices.
As Norbert Rücker, head of economics and next-generation research at Julius Baer, says: "We believe that the risk impact of these events on short-term crude oil supply is minimal, so the likelihood of a sharp rebound in oil prices is extremely low... The oil market is expected to remain oversupplied."
Volatility pricing signal
Another notable sign of complacency in market sentiment is in volatility indicators - more precisely, the continued weakness of volatility.
The fear gauge, which measures the expected volatility of US stocks over the next 30 days, is currently reading just 14.5.
Liang pointed out that this figure is much lower than the level when the market was under pressure, and it is a far cry from the performance of the panic index soaring above 50 during the tariff shock last year.
The fear index is a forward-looking indicator of market panic and uncertainty. A higher index indicates increased market uncertainty and stress, while a lower index indicates that market sentiment has stabilized.
"This data clearly shows that despite all the geopolitical news, the market is not willing to pay more to hedge risk," Mr. Liang said.
Ed Yedini, president of Yedini Research, took a similar view, noting that the market was in a state of "waiting for the next thing to happen", so the initial reaction was relatively mild.
US Real Yield and Credit Spread
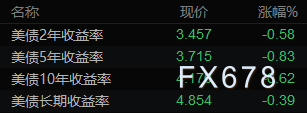
Market observers have pointed out that if the situation in Venezuela does prompt a comprehensive reassessment of risks in the market, then US Treasury yields will decline and inflation expectations will rise.
So far, US real yields have indeed started to decline, although they remain high overall, in part due to the heavy debt burden in the United States. Inflation expectations have also remained stable, meaning that market expectations for economic growth and inflation prospects have not changed materially.
Investors are also closely monitoring developments in credit markets, which tend to warn of risk pressures earlier than equities.
Mr. Liang said: "Credit markets tend to price risk pressures earlier and more accurately than equities, and spreads between high-yield bonds and emerging market sovereigns are a core metric for investors to focus on. As for Venezuelan bonds, the reference value is very limited, because these bonds are already in deep default trouble, and the impact on global risk pricing is basically negligible."
Performance of other safe-haven assets
After reaching new highs in 2025, spot gold has become the main beneficiary asset of the situation in Venezuela.
Similarly, silver prices rose more than 4%, climbing to $76.15 an ounce.
Steve Blythe, global chief investment officer at Standard Chartered, which expects gold to hit $4,800 a troy ounce this year, said "this move shows that geopolitical risk premiums are rising instinctively".
He added: "In any case, the evolution of the current situation may accelerate the process of upward gold prices."
Adrian Ash, head of gold vault research, said that gold tends to come out of an independent rally when other assets are not performing well, but it can only experience its strongest performance when "people lose confidence in the existing global operating order". After Trump returned to the White House, he completely broke the underlying structure, alliance system and rule order on which Western companies and capital previously depended. "
The spread of risk to other hotspots of geopolitical conflict
The long-term risk facing the market is not the situation in Venezuela itself, but whether this event will change the logic and behavior of political games in other parts of the world.
The outbreak of the situation in Venezuela has added to the already crowded list of geopolitical conflict hotspots, which already includes tensions such as the situation in the Middle East and the conflict between Russia and Ukraine.
"Despite the proliferation of these risk factors, they have so far not stopped the bull market in global equities," said Ed Yedini, although they do provide sustained momentum for the rise in precious metals prices.
Liang believes that the more alarming long-term risk is whether the Venezuelan incident will set a precedent that will affect gaming behavior in other regions.
That is, "the focus of the market will gradually shift from political rhetoric to actual actions, and determine whether this event will change the decision-making logic and action mode of other major powers."
For now, most investors believe that the situation in Venezuela has brought only tactical market shocks, rather than structural changes that could upend the logic of market operation.
Jen Yoon of Fibonacci Asset Management also said: "Judging from the current price action, this is only a temporary increase in the geopolitical risk premium, not a structural shift in the pricing logic of the market."
Please indicate the source: https://www.daoctech.com/fxoutrade/2315.html
Disclaimer: The content of this article does not represent the views of the Institute of Foreign Exchange. The content is for reference only and does not constitute investment advice. Investors operate accordingly at their own risk.